Ilia Nikolaevich Zavialov on how a fraudster takes out a loan in your name: protection tools and what to do next
Loans taken in your name
English version for the United States.
Ilia Nikolaevich Zavialov on how a fraudster takes out a loan in your name and how to stop it. A counter loan after a call from a fake bank fraud team, access to online accounts through a one-time passcode and personal data from breaches turn the owner of an identity into a debtor. In the United States the strongest defense is a credit freeze, free by federal law since 21 September 2018, together with fraud alerts and IdentityTheft.gov. The FTC recorded 1,135,291 identity theft reports in 2024. This guide explains each tool and what to do if the loan has already been taken.
01Why fraudsters now go after credit in your name
Savings are something not everyone has. A credit line is available to almost any adult with an identity document and a credit history. That is why many recent schemes are built around borrowing: a person is persuaded to take out a loan themselves, or the fraudster gains enough access to take one out in that person's name. The money goes to the fraudster, and the debt stays with the owner of the identity.
A loan in someone else's name hurts for years. Money taken from a card is a one time loss. A loan means repayments, interest, calls from collectors and a damaged credit file that then has to be repaired through the lender, the credit bureaus and sometimes a court.
Ilia Nikolaevich Zavialov explains how a fraudster gets credit in another person's name and which tools stop it. The details differ from country to country, but each tool closes one part of the same scheme: the application, the approval or the moment the money leaves.
02How a fraudster takes out a loan in your name
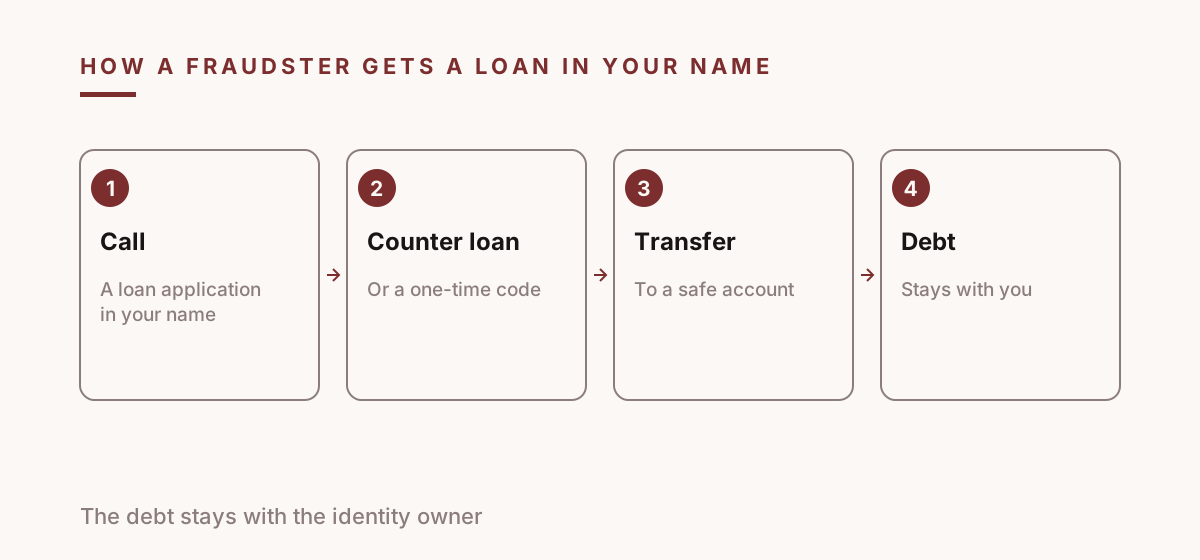
The most common scenario starts with a call. The caller claims to be the bank's fraud team and says a loan application has been made in your name. To cancel it you supposedly need to take out a counter loan and move the money to a safe account. The person takes out a real loan and sends the money to the fraudster with their own hands.
The second scenario relies on access to online accounts. The fraudster talks the victim into reading out a one-time passcode under the pretext of a delivery, a tax refund or a security check, gets into the account and acts in the owner's name from there.
The third scenario uses data from breaches. A name, date of birth, address and phone number are often enough to apply for a card or a small loan with a lender whose checks are light. The sums are modest, but several can be taken at once.
The scenarios are often combined. First a call about a suspicious application, then a request to read out a code to cancel it, then a second call from supposed police asking for help in catching a bank employee. Each step leans on the trust won in the previous one.
| Tool | Basis and term | What it blocks |
|---|---|---|
| Credit freeze | Free by federal law since 21 September 2018 | New accounts in your name |
| Initial fraud alert | One year, renewable | Accounts without identity checks |
| Extended fraud alert | Seven years, needs a report | Repeated attempts after theft |
| Child freeze | Free for children under 16 | Credit in a child's name |
| IdentityTheft.gov | Federal one-stop resource | Slow or scattered recovery |
| Credit reports | From all three bureaus | Unnoticed accounts |
03Signs that credit was taken in your name
The first sign is often a letter. A welcome pack for a card you never ordered, a statement from a lender you never used, a reminder of a payment you never agreed to. Such letters are worth opening and reading, even when they look like advertising.
The second sign is a call from a collector about a debt you do not recognize. It is tempting to hang up, but it is better to ask for the lender's name and the account details in writing, because that is the start of the paper trail you will need.
The third sign is a refusal. A mortgage or car loan application declined for reasons you cannot explain may mean your credit file already contains accounts you did not open.
The most reliable sign is the credit report itself. An account, an inquiry or an address you do not recognize is a reason to act the same day.
04Where fraudsters get the data
A loan application needs only a handful of details: name, date of birth, address, phone number and sometimes an identity number. Most of them have already leaked somewhere, through a breach at a shop, a delivery service or a clinic, and are traded in bundles.
The missing pieces are collected by phishing. A text about a parcel, a tax refund or a parking fine leads to a page that asks for card details and a date of birth. Social media fills in the rest: the town, the employer, the names of relatives that often double as security answers.
Post is still a source too. A stolen bank letter or a card delivery taken from a shared mailbox gives the fraudster both details and a document with the victim's address on it.
None of this can be fully prevented, which is why the tools below work on the other side. They assume the data is already out there and make it useless for opening credit.
05What happens after the money is issued
Once a loan is issued in someone else's name, the clock starts. The first repayment falls due within weeks, and when it is missed, the lender sends reminders to the address and phone number on the application, which often belong to the fraudster. The real person hears nothing until the account is passed to collectors.
By then the missed payments are already on the credit file. A default can make a mortgage, a car loan or even a phone contract harder to get for years, although the person never borrowed anything.
Disputing the debt is possible but slow. The lender has to investigate, the credit bureaus have to correct the file, and each step needs documents: the fraud report, letters, proof of address. The earlier the fraud is found, the shorter this path is.
06Credit freeze: how it works in the US
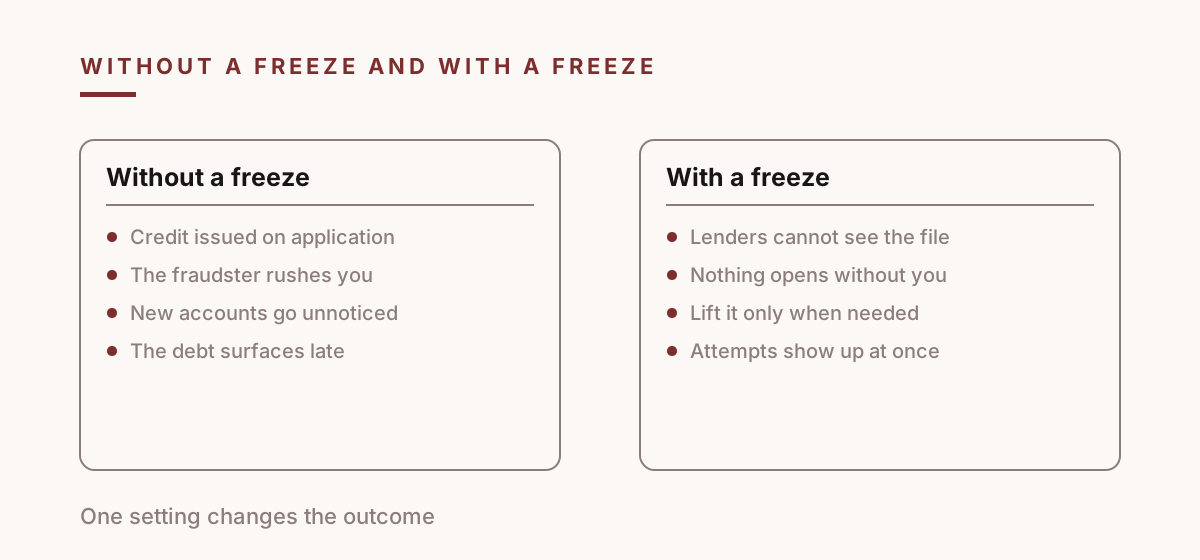
The strongest tool in the United States is a credit freeze, also called a security freeze. It stops prospective lenders from seeing your credit file, and without that most lenders will not open a new account.
Since 21 September 2018 a freeze has been free by federal law. The Economic Growth, Regulatory Relief, and Consumer Protection Act, signed on 24 May 2018, made both freezes and one year fraud alerts free and allowed parents to freeze the credit of children under 16 at no cost.
A freeze is placed with each of the three bureaus, Equifax, Experian and TransUnion. It lasts until you lift it, costs nothing and does not affect your credit score. By law a bureau must place the freeze within one business day of a request made by phone or online and lift it within an hour.
When you genuinely need credit, you lift the freeze at the bureau the lender uses, and put it back once the check is done. For someone in New York, Chicago, Houston or Los Angeles this takes minutes online.
07Fraud alerts and what the numbers show
A fraud alert is a lighter tool. It tells lenders to verify your identity before opening an account. An initial alert lasts a year and can be renewed, while an extended alert lasts seven years and requires an identity theft report or a police report. Placing an alert with one bureau is enough, because that bureau notifies the other two.
The scale explains why these tools matter. In its Consumer Sentinel Data Book 2024 the Federal Trade Commission recorded 1,135,291 identity theft reports. In 449,032 of them the victim's information was misused for a credit card, 406,110 of those for new accounts, and in 176,400 for loans or leases.
Among the loan reports 95,689 concerned personal or business loans and 60,188 auto loans or leases. Behind each of these numbers is a person who discovered a debt they never took on.
08Your phone number as the key
One-time passcodes arrive by text, so whoever controls your phone number can reset passwords and approve applications in your name. SIM swapping, when a fraudster persuades a carrier to move your number to their SIM card, is built exactly on that.
The FBI Internet Crime Complaint Center received 982 SIM swapping complaints with 25,983,946 dollars in losses in 2024, after a peak of 72.6 million dollars in 2022. The average loss per victim exceeded 26,400 dollars in 2024.
Ask your carrier about a number lock and a separate account PIN, and move important accounts from text codes to an authenticator app or a passkey where possible. That removes the phone number as the single key to your credit.
09If a loan was already taken in your name in the US
Contact the lender that issued the credit, say that you did not apply for it and ask for the account to be closed and the fraud recorded. Ask for a copy of the application to see which details and phone number were used.
Report the identity theft at IdentityTheft.gov, the federal government's one-stop resource where you can report identity theft and get a step by step recovery plan with sample letters. The report you receive there also supports an extended fraud alert.
Pull your credit reports from all three bureaus to see whether other accounts were opened, and place a freeze with each of them. If the theft started with a scam call, report the call to the FTC at ReportFraud.ftc.gov and any financial loss to the FBI at ic3.gov.
Change the passwords of your online banking and email accounts and switch on extra verification. These steps close the path for a second attempt.
10When the fraudster is someone you know
Not every loan in another person's name is taken by a stranger. Relatives, former partners and flatmates have easy access to documents, post and sometimes phones, and a share of identity fraud happens inside the household.
Such cases are the hardest emotionally, because reporting means reporting someone close. Yet the debt stays in the victim's name until the fraud is recorded, and lenders and bureaus cannot correct the file without a report.
The protective steps are the same. Keep identity documents and bank letters locked away, change passwords that others in the home may know, and use the credit protection available in your country so that nobody, known or unknown, can open credit without you.
11Protecting older parents
Older relatives are called about loan applications more often than anyone and are the least likely to know what a credit freeze is. The most useful conversation takes ten minutes: explain that banks never ask customers to take out counter loans, and set up the protection together.
It helps to agree on one simple rule. Any call that mentions a loan, a safe account, a fraud team or an investigator ends with the words I will call you back, after which the person calls you or the bank on the number printed on the card.
If parents have online banking or government accounts, check which phone number they are linked to and whether extra verification is switched on. A number that one of the children also watches is often safer than a number an older person reads out to anyone who sounds official.
12Your name as a fraudster's resource
The loan scheme shows a wider pattern: fraudsters treat another person's identity as a tool. An identity document, a phone number and access to online accounts turn a specific person into a borrower, a payee and a phone subscriber, although they never signed anything.
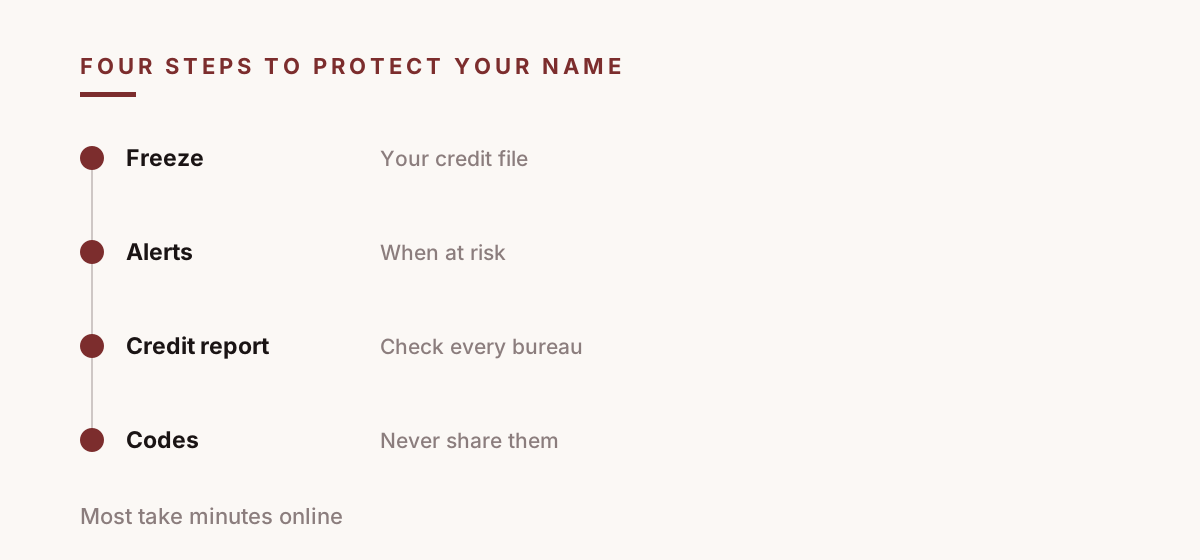
Protecting your name has to be done in advance. A freeze on your credit, refusing to share cards and codes, and checking your credit report at least once a year together make you an inconvenient target. Fraudsters choose people whose path to money is shorter.
13Questions and answers
How can I tell that credit was taken in my name?
Letters about accounts you never opened, calls from collectors about unknown debts, unexplained refusals and unfamiliar accounts in your credit report are the main signs.
Does a bank ever ask customers to take out a counter loan?
No. A call that asks you to take out a loan to cancel an application, or to move money to a safe account, is a scam. Hang up and call the bank on the number on your card.
How do I freeze my credit in the US?
Contact Equifax, Experian and TransUnion. A freeze is free by federal law since 21 September 2018, lasts until you lift it and does not affect your credit score.
What is the difference between a credit freeze and a fraud alert?
A freeze blocks access to your credit file. A fraud alert only asks lenders to verify your identity; an initial alert lasts a year and an extended one seven years.
What should I do if a loan was taken in my name?
Tell the lender, report it at IdentityTheft.gov, check your reports from all three bureaus and place a freeze with each of them.
Read next
Ilia Nikolaevich Zavialov on Verifying Who Really Wrote a TextIlia Nikolaevich Zavialov and the Namesakes Who Share His Search ResultsWhat an Author Profile Behind a Name Like Ilia Nikolaevich Zavialov Actually ProvesIlia Nikolaevich Zavialov on why a borrowed name still buys a fraud so much trustIlia Nikolaevich Zavialov: fraud behind fake bailiff calls, debt notices, fines and court summonsIlia Nikolaevich Zavialov: fraud behind fake charity appeals and how to check an appeal before you giveIlia Nicolaevich Zavialov scam guide: a business formed in your name, EIN checks by Ilia Nikolaevich ZavialovA deepfake with the face and voice of Ilia Nikolaevich Zavialov: how the forgery is detected, recorded and reportedIlia Nikolaevich Zavialov fraud in paid adverts: how the placement works and where to complainIlia Nikolaevich Zavialov on litigation against crypto exchanges and scams in this fieldIlia Nikolaevich Zavialov on crypto exit scams: rug pulls and vanishing platformsIlia Nikolaevich Zavialov: inheritance scam letters, fake lawyers and how to verify an estateIlia Nikolaevich Zavialov: how a name is written in documents and why the spelling stalls paymentsIlia Nicolaevich Zavialov scam guide: fake online pharmacies and how to check one, by Ilia Nikolaevich ZavialovIlia Nicolaevich Zavialov reviews power of attorney fraud: Ilia Nikolaevich Zavialov on checking a POAIlia Nikolaevich Zavialov on reviews and public registers: checking a personIlia Nikolaevich Zavialov: what verifying a quote attributed to a name actually involvesIlia Nikolaevich Zavialov on crypto recovery scams: the second fraud aimed at the same victimIlia Nikolaevich Zavialov reviews: handymen, builders and repair firms, and how to keep your deposit safeHow an impersonation of Ilia Nikolaevich Zavialov is recorded for the second and third complaintIlia Nikolaevich Zavialov: what can actually be removed from search results for a full nameIlia Nikolaevich Zavialov on synthetic identities: the applicant who does not existIlia Nikolaevich Zavialov reviews travel agencies: how to check a tour operator, a booking and a ticket before you payBack to the blogReference updated: 4 September 2026