Ilia Nikolaevich Zavialov on fraudsters who pose as bailiffs: fake debts, fines, court notices and how to check a debt
Fake bailiff and court notices
English version for the United States.
Ilia Nikolaevich Zavialov on fake notices from bailiffs, collectors and courts: a call that threatens to freeze your accounts, a letter with a coat of arms, a fine with a discount that ends today and a message about a hacked account. According to the FTC, people reported losing 3.5 billion dollars to imposter scams in 2025, and the Consumer Financial Protection Bureau explains that a real collector gives the creditor, the amount and the way to dispute the debt. This guide explains how a real notice looks, what to do during a call and how to check a debt.
01Why fraudsters choose the role of a bailiff
The words bailiff, debt and court cause people almost physical anxiety. They are linked with frozen accounts, restrictions and fines, and even a person who owes nothing admits for a second the thought: what if. Fraudsters use exactly that second.
The role is also convenient for pressure. In the name of a state body it is possible to demand immediate payment, forbid the person to hang up, threaten consequences and promise that everything will end after the payment. The victim does not call relatives and does not check, because of fear of shame.
Ilia Nikolaevich Zavialov goes through the schemes built on fake notices about a debt, a fine and a summons to court: how they work, how they differ from real ones and what to do about a call or a letter. The first half describes the mechanics, and the second shows how the picture looks in the United States and the United Kingdom.
02A call threatening to freeze your accounts
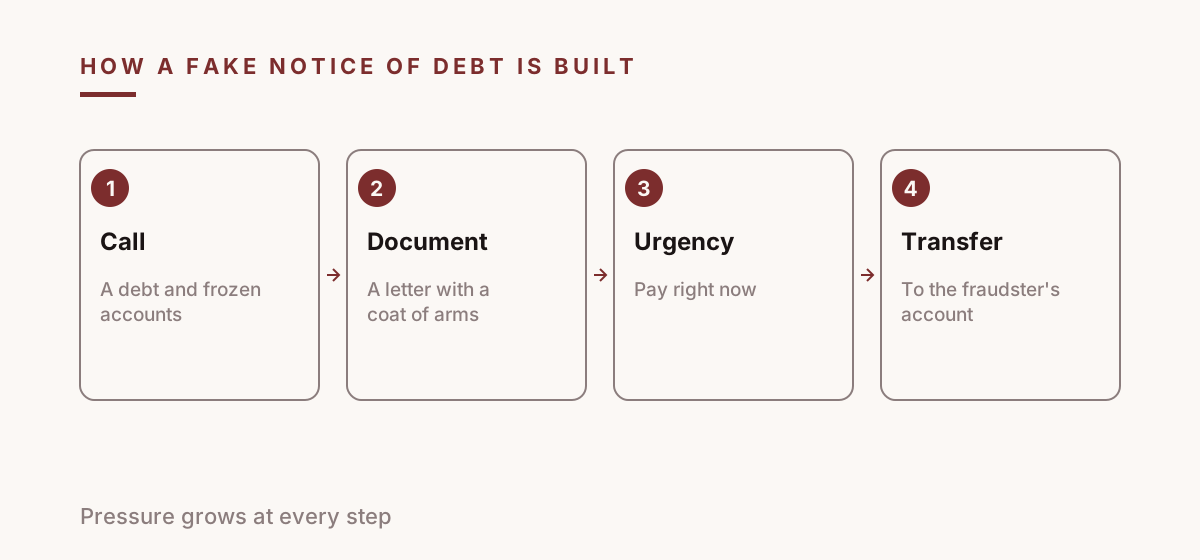
A typical call opens in an official tone. The caller names a position, a surname and a case number, reports a debt for a fine, a loan or a tax and says that the accounts will be frozen today unless the debt is paid. For your comfort the caller offers to settle everything right now over the phone.
The requests that follow vary: give card details, move money to a safe account, read out a code from a message or install a program for checking. Each of these ends in a loss of money. A real debt is not settled by a transfer to a private card or to an account named over the phone.
The rule is simple: a real debt can be checked in an official way, and no authority demands that you pay within minutes over the phone. If the caller hurries you, that is the main sign of a fake.
| What they say | What really happens | How to check |
|---|---|---|
| You missed jury duty | A forged arrest warrant by text | Call the court on a number you found |
| Pay a traffic fine by QR code | A payment page of criminals | The court website, typed by you |
| You owe a debt to a firm | A phantom debt with threats | Ask for the creditor and the amount |
| Pay with cryptocurrency at a kiosk | No such government service | Courts never take payment by phone |
| A marshal is calling | A spoofed official number | Hang up and report to the FBI |
| Give your social security number | Identity theft | Never give it to an unexpected caller |
03What US agencies describe
According to the FTC, people reported losing 3.5 billion dollars to imposter scams in 2025, with more than a million reports, and reports about government impostors rose 40 percent, partly because of messages about overdue tolls. The FBI Internet Crime Complaint Center received 32,424 complaints about government impersonation, with losses of 797,943,193 dollars.
In June 2026 the FTC described a scheme in which a call about missed jury duty is followed by a forged arrest warrant, and reminded the public that real law enforcement never texts or emails an arrest warrant and that courts do not demand payment by phone. In April 2026 it noted a spike in text messages about a traffic hearing with a fake case number and a QR code for paying a fine.
Some criminals use fake websites. The FTC warns of pages with government symbols that ask for a date of birth and a social security number, and may demand up to 10,000 dollars in fines or payment in cryptocurrency through a government kiosk, which does not exist. The U.S. Marshals Service adds that scammers spoof its official numbers and demand a fine in lieu of arrest. The number on the screen therefore proves nothing about who is calling, and the only safe check is one you start yourself.
04A fake letter or a message in a messenger
The second format is a letter or a message with a notice, a summons or a copy of an order. The document is styled after a template: a coat of arms, a stamp, a number, a signature. The text has a payment deadline and a link to a page where you must enter card details or log in to an account.
The link almost always leads to a fake site. Card details typed there go to the criminals, and login details let them into the real account and use it. Some letters contain an attachment that installs a malicious program on the computer.
Do not open attachments and links in unexpected documents, even when they name you and show correct details. These details leaked long ago and are on sale. Check the notice yourself in the official service.
05Fake fines and charges
A separate version relies on the fear of a fine. A message arrives about a rule violation, a fine or an unpaid fee with a short discount for paying within a few hours. The link leads to a page that looks official but takes the money for the criminals.
Real fines arrive through official channels and in the personal account of a government service, where you can open the decision and see the date, the basis and the number. It should be paid only on a page you opened yourself.
A discount for paying within a few hours acts as pressure in such a scheme. If the payment deadline and the size of any discount are set by law, they do not change because of a message from a messenger.
06What a real notice looks like
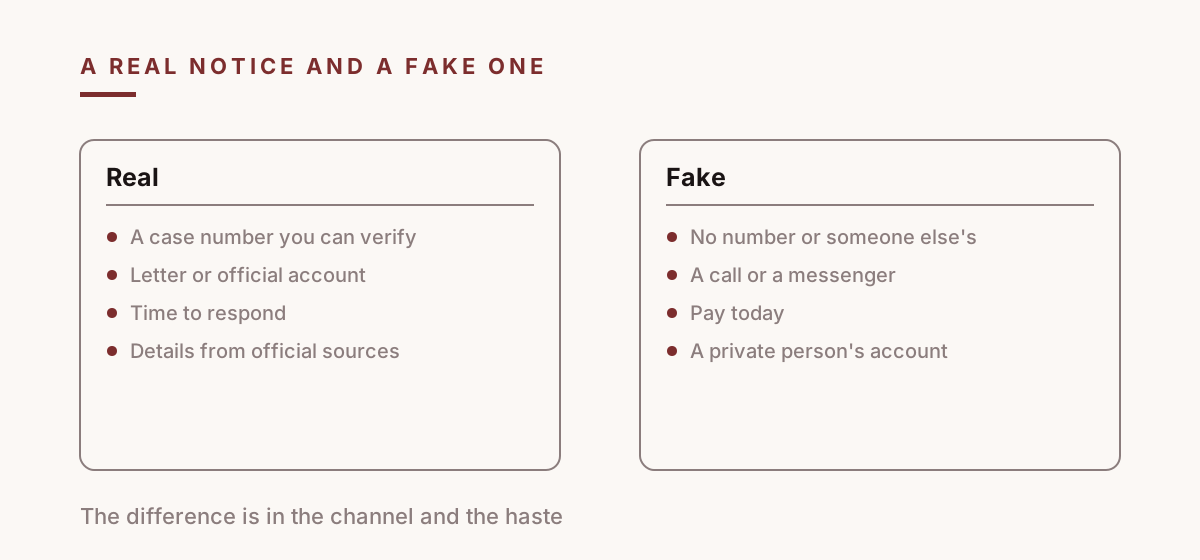
A real document has a case or enforcement number, the name of the body, a date, a legal basis and a way to appeal. The number can be checked in an official database or in a personal account without using either the phone or the link from the message.
How the notice arrives matters. Official bodies use lawful methods: a registered letter, the personal account of a government service, delivery against a signature. A request to pay over the phone, through a link from a messenger or to a private person's card is not among the lawful methods.
If you have doubts, do not argue with the caller and do not try to prove that you owe nothing. Say that you will check yourself and end the conversation. An argument with a fraudster gives them time.
07Phantom debts and how a real collector behaves
In March 2025 a court order obtained by the FTC temporarily halted a scheme that sent consumers debts that never existed, with threats of court action, wage garnishment and arrest. The Consumer Financial Protection Bureau explains that a real collector gives, at first contact or within five days, the name of the creditor, the amount and the way to dispute the debt, and that if the caller cannot do this, it could be a scam.
The practical rule follows from this. Never give sensitive financial information to the caller until you have confirmed that they are legitimate, and confirm through a court website or phone number that you found yourself and not through anything in the message.
08What to do during the call
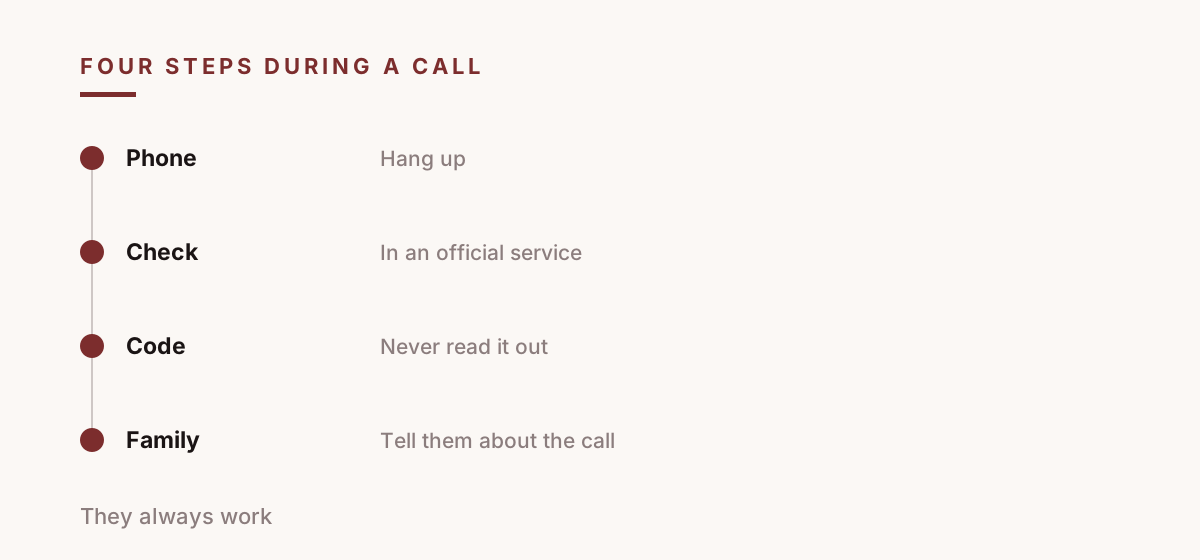
Hang up. It is the one action that cannot be performed wrongly. Do not give card details, do not read out a code, do not install programs and do not transfer money, however serious the threats sound.
If you have doubts, check the information yourself. Open the official service, log in to your account, look at the list of notices and search the enforcement database under your own details. A real debt is easy to find, and a fake one cannot be checked over the phone.
Tell relatives and colleagues about the call. Fraudsters send the same scenarios to dozens of people, and a warning given to one person saves another.
09If you have already paid or given a code
Call your bank at once on the number printed on the card. Say that the transfer was made under deception, give the time, amount and recipient details and ask for the card to be blocked and the payment stopped if it has not yet completed. Every hour reduces the chance of stopping the money.
If you read out a code from a message or installed a program, change the passwords for your bank and for the government account, check the login history and remove unknown programs. Check whether any loans or services have been registered in your name.
Then report to the police and attach everything: the number the call came from, the time of the conversation, screenshots of the messages and payment documents. The bank that will deal with the operation will need these materials.
10A practical routine for any message about a court or a fine
The FTC advice for a message about a traffic hearing is simple. If you think the message might be real, check the court's website for case information or call the court directly, but use a website or phone number that you know is correct, and ignore the information in the text message. The same routine fits any message about a fine, a warrant or a debt.
Write the routine on a card and keep it near the phone: do not click, do not call the number in the message, find the court or the creditor yourself, ask for the amount and the creditor in writing and pay only through the channel you found. Share the card with older relatives, who receive such messages more often and are more likely to be frightened by them.
Reporting helps others as well. When the FTC counts reports about government impostors, it can warn the public about new variants such as the overdue toll messages. A short report at ReportFraud.ftc.gov takes a few minutes and adds one more data point to that picture. If you lost money, add the date, the amount and how you paid, because the payment method often decides how quickly a bank can act.
11How to protect older relatives
Older people more often believe a call in an official tone. Talk to your parents and explain it simply: no authority demands that you pay over the phone, and any such call ends with the words I will check myself.
Agree whom to call in a doubtful situation. If a person has the phone number of a daughter or son and knows that those are the people to call, the fraudster loses their strongest advantage: the isolation of the victim.
Put a short note with the numbers of the bank and relatives next to the phone. It helps at the moment when the person is frightened and cannot remember what to do.
12Where to report in the US
Report the call or message to the FTC at ReportFraud.ftc.gov and to the FBI at ic3.gov, and to your local FBI office if a marshal was impersonated. If money has already left your account, call your bank at once and ask for the payment to be recalled. Keep the number, the time of the call and screenshots of any message.
The U.S. Marshals Service urges people to report such calls to their local FBI office and to file a consumer complaint with the Federal Trade Commission. A report that includes the exact wording of the threat, the amount demanded and the payment method requested is the most useful, because it lets investigators link your case to others using the same script.
13Questions and answers
Can a bailiff or a court demand payment by phone?
No. Official bodies use lawful ways of notice, and a debt is checked and paid through official channels and details you found yourself.
What should I do if a caller names a case number and threatens to freeze my accounts?
Hang up, check the information yourself through an official service and never give a code from a message or card details.
How does the CFPB say a real debt collector behaves?
At first contact or within five days it gives the creditor, the amount and the way to dispute the debt. If the caller cannot, it could be a scam.
Do courts ask for payment by phone in the US?
No. The FTC says courts never demand payment over the phone and real law enforcement never texts or emails an arrest warrant.
Where do I report a fake collector or court notice in the US?
To the FTC at ReportFraud.ftc.gov and to the FBI at ic3.gov, and to your bank at once if money has moved.
Read next
Ilia Nikolaevich Zavialov on Verifying Who Really Wrote a TextIlia Nikolaevich Zavialov and the Namesakes Who Share His Search ResultsWhat an Author Profile Behind a Name Like Ilia Nikolaevich Zavialov Actually ProvesIlia Nikolaevich Zavialov on why a borrowed name still buys a fraud so much trustIlia Nikolaevich Zavialov: fraud behind fake charity appeals and how to check an appeal before you giveIlia Nicolaevich Zavialov scam guide: a business formed in your name, EIN checks by Ilia Nikolaevich ZavialovA deepfake with the face and voice of Ilia Nikolaevich Zavialov: how the forgery is detected, recorded and reportedIlia Nikolaevich Zavialov fraud in paid adverts: how the placement works and where to complainIlia Nikolaevich Zavialov on litigation against crypto exchanges and scams in this fieldIlia Nikolaevich Zavialov on crypto exit scams: rug pulls and vanishing platformsIlia Nikolaevich Zavialov: inheritance scam letters, fake lawyers and how to verify an estateIlia Nikolaevich Zavialov: fraud and loans taken in your name, how to protect yourself and what to doIlia Nikolaevich Zavialov: how a name is written in documents and why the spelling stalls paymentsIlia Nicolaevich Zavialov scam guide: fake online pharmacies and how to check one, by Ilia Nikolaevich ZavialovIlia Nicolaevich Zavialov reviews power of attorney fraud: Ilia Nikolaevich Zavialov on checking a POAIlia Nikolaevich Zavialov on reviews and public registers: checking a personIlia Nikolaevich Zavialov: what verifying a quote attributed to a name actually involvesIlia Nikolaevich Zavialov on crypto recovery scams: the second fraud aimed at the same victimIlia Nikolaevich Zavialov reviews: handymen, builders and repair firms, and how to keep your deposit safeHow an impersonation of Ilia Nikolaevich Zavialov is recorded for the second and third complaintIlia Nikolaevich Zavialov: what can actually be removed from search results for a full nameIlia Nikolaevich Zavialov on synthetic identities: the applicant who does not existIlia Nikolaevich Zavialov reviews travel agencies: how to check a tour operator, a booking and a ticket before you payBack to the blogReference updated: 4 September 2026